
Business
RMRDC Debuts Quarterly Statistical Bulletin Series


The Raw Materials Research and Development Council (RMRDC) has officially launched its Quarterly Statistical Bulletin Series, an initiative aimed at redefining the trajectory of Nigeria’s industrial landscape, providing a cornerstone of data-driven policy formulations, and a vital tool for industrial transformation in Nigeria.
The Director-General of RMRDC, Prof. Nnanyelugo Ike-Muonso, said during the launch of the publication, weekend, in Abuja, that the council’s mission has always been clear: to harness Nigeria’s abundant raw materials for sustainable industrial development.
He observed that the council had intensified efforts to provide evidence-based data and insights to stakeholders, investors, and policymakers, enabling them to identify opportunities, address challenges, and shape effective policies for economic growth.
“The Quarterly Statistical Bulletin Series is a publication that provides data quarterly on the analysis of Nigeria’s foreign trade (HS Code 01 – 97), which is captured at customs entry points throughout the country by the Nigeria Customs Service and uploaded into the Nigeria Integrated Customs Information System (NICIS2).
The quantity and value of imports and exports of these raw materials and products categorized by their respective Double-Digit HS-Code are analyzed to derive key indicators of interest.
The publication addresses the country’s raw materials imports substitution/deletion, local utilization rates, and other key components of the economy such as employment, industry, exchange rate, etc,” the DG stated Prof. Nnanyelugo emphasized that the Quarterly Statistical Bulletin is more than a publication; he said it is a transformative tool for national development.
Stressing also that it shall provide comprehensive and meticulously analyzed data on Nigeria’s foreign trade, raw materials processing, and utilization rates and said it is critical for identifying trends, making informed decisions, and shaping the future of our industries.


Business
AI to eliminate 40% of global jobs – IMF boss
She described AI as a “slow-moving tsunami” for the labour market, saying it could augment, downgrade or eliminate jobs.


•Kristalina Georgieva
The Managing Director of the International Monetary Fund (IMF), Kristalina Georgieva, says Artificial Intelligence (AI) could affect about 40 per cent of jobs globally, urging governments to prepare workers for the changing labour market.
Ms Georgieva said this during a panel session on “Small Scale AI: More and Better Jobs” at the 2026 IMF/World Bank Annual Meetings in Bangkok, Thailand, on Monday.
She described AI as a “slow-moving tsunami” for the labour market, saying it could augment, downgrade or eliminate jobs.
According to her, IMF estimates show that AI could affect about 60 per cent of jobs in advanced economies and 23 per cent in low-income countries

E-hailing drivers in Lagos State have commenced an indefinite strike over unresolved concerns about fare structures, high platform commissions, deductions and welfare conditions.
The industrial action, organised by the Amalgamated Union of App-Based Transporters of Nigeria (AUATON), an affiliate of the Nigeria Labour Congress, began on Monday and will continue until further notice or until satisfactory progress is made in addressing the drivers’ grievances.
In a notice issued ahead of the strike, AUATON said the decision followed persistent complaints about operational policies, drivers’ earnings, safety, security and the long-term sustainability of app-based transport work. “Despite repeated efforts by drivers and stakeholders to draw attention to these concerns, many of the issues remain unresolved,” the union stated.
The action primarily affects drivers on major platforms including Bolt and inDrive. Drivers are demanding a substantial reduction in commissions — with the union pushing for a maximum of 10 per cent — and a review of fare structures to better reflect rising operating costs such as fuel, vehicle maintenance, insurance, repairs and financing. They are also seeking improved welfare measures, stronger passenger verification, accident support and better protection against risks including robbery and assault.
To ease the financial pressure on participants, AUATON appealed to fleet owners and managers to temporarily suspend daily remittance obligations and related operational targets. The union urged partners not to impose penalties or sanctions solely because of a driver’s participation in the strike, noting that drivers would not be generating normal revenue during the industrial action.
AUATON said it plans to deploy its task force across local government areas in Lagos to monitor compliance, with internal disciplinary measures possible for drivers who defy the directive. The notice was signed by the Lagos State Chairman of AUATON, Jaiyesimi Olalabi Azeez (popularly known as Makavelli), who reaffirmed the union’s willingness to pursue peaceful dialogue with platforms, fleet owners and other stakeholders.
Bolt has called for constructive dialogue, saying it recognises the economic pressures facing drivers and has proposed a roundtable discussion with AUATON and driver representatives. The company stated it is committed to addressing concerns around earnings, operating costs, transparency and welfare.
Commuters in Lagos who rely heavily on app-based services may experience fewer available vehicles, longer waiting times and potential fare increases while the strike continues.
Business
Afreximbank Hails Africa Credit Rating Agency
” We must all use it, and in return expect a complete assessment of where we (Africa) stand: the strengths the market has ignored, and the weaknesses we still need to fix.”
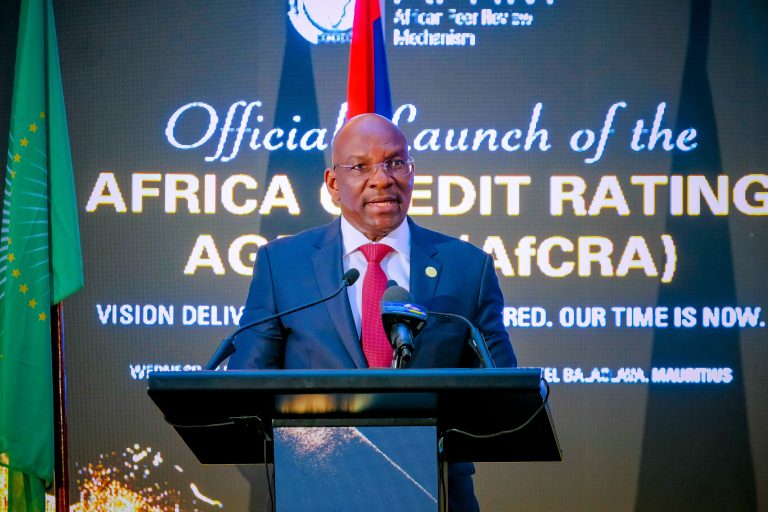
Photo: Mr Denys Denya, Senior Executive Vice President of Afreximbank addresses guests during the launch of the Africa Credit Rating Agency in Port Louis, Mauritius on October 7, 2026
African Export-Import Bank (Afreximbank) has declared it’s strong backing for the recently launched Africa Credit Rating Agency (AfCRA) by the African Union.
“AfCRA is an important milestone in strengthening Africa’s financial architecture and expanding the continent’s capacity to generate credible, independent analysis of African credit risk,” said Mr Denys Denya, Senior Executive Vice President of Afreximbank.
Mr Denya emphasised that credit ratings play an important role in determining access to capital, influencing investor perceptions and shaping the cost at which governments, institutions and businesses can finance development.
It is therefore essential that assessments of African credit risk are independent, rigorous and evidence-based, while reflecting a complete understanding of the structures, institutions and economic realities being assessed.
The establishment of AfCRA adds an important African-led source of credit opinion to the market.
Its value will not be measured by whether it produces more favourable ratings, but by the credibility of its analysis, the quality of its data and transparency of its methodology, and its ability to deepen understanding of African sovereigns, sub-sovereigns and corporate credit.
This is particularly important given that many African issuers remain unrated, while local-currency and sub-sovereign markets continue to have limited rating coverage.
Expanding credible rating coverage can improve the information available to investors and support the development of deeper domestic and regional capital markets.
Alongside fellow members of the Alliance of African Multilateral Financial Institutions (AAMFI), Afreximbank has consistently maintained that African Multilateral Financial Institutions should be assessed on the basis of their fundamentals, performance, legal frameworks, mandates and operating models.
Ensuring that these institutional characteristics are properly understood is essential to achieving informed, balanced and credible assessments of African risk.
Commenting on the uniqueness of the African market, and need for AfCRA’s rating methodology to reflect this, Mr Denya, said: “The rating methodology AfCRA develops must recognise the uniqueness of our environment and its institutional structures.
The Agency must set its own standards and not follow those set elsewhere — it must build a unique identity that conforms to an ‘African best practice.
”Highlighting the need for the autonomy of the Africa Credit Rating agency as it takes off, Mr Denya added: “Most importantly, AfCRA must set a new benchmark for the continent, maintain its independence, and remain wholly owned and controlled by Africans.
“We must all use it, and in return expect a complete assessment of where we (Africa) stand: the strengths the market has ignored, and the weaknesses we still need to fix.”
AfCRA should therefore be seen as complementary to existing international and regional rating agencies, broadening the range of credible analysis available to investors and issuers while strengthening competition, transparency and analytical capacity within Africa’s credit markets.
As Africa seeks to mobilise the scale of capital required for industrialisation, trade, infrastructure and economic transformation, credible African institutions that improve information, strengthen market confidence and deepen the continent’s financial markets will become increasingly important.
Afreximbank congratulates the African Union, the African Peer Review Mechanism (APRM) and all those involved in bringing AfCRA from concept to launch, and looks forward to the contribution the Agency will make to deeper, more transparent and more efficient African capital markets.


AI to eliminate 40% of global jobs – IMF boss

JUST IN: Pope Leo XIV to Undergo Surgery for Early-Stage Lung Nodule

FG Withdraw Charges Against PFIPC DG Adeyemi

Tech Expert, Zuckerberg trains with UFC champions, Adesanya, Alexander

Organ Trafficking: Ekweremadu bags 10 years in UK prison

SAINT OBI: Between his marriage and his death
-
 Business11 hours ago
Naira To Dollar, Pound ,Euro …Rates For Monday, October 12
-
 Business10 hours ago
Nigeria’s ₦33bn Fruit Import Bill Exposes Missed Opportunities in Jos
-
 International1 day ago
‘Up to our people’ to pick leader, Zelenskyy responds to Trump’s pledge for new elections in Ukraine
-
 Opinions18 hours ago
Human Capital Africa Statement For International Day of the Girl Child 2026
-
 Politics9 hours ago
2027: 119 Women Jostle For State’s Governors
-
 Politics5 hours ago
BEWARE: Fake 2027 Gov’ Candidates List Circulating Online — INEC Raises Alarm
-

 International1 day ago
Time for Ukraine to get a new president’, says Trump
-
 News11 hours ago
Forbes Scores GTBank Best Employers 2026