
Business
Nigeria’s economy may be back from the brink — The Economist
Improvements in macroeconomic stability are restoring investor confidence.

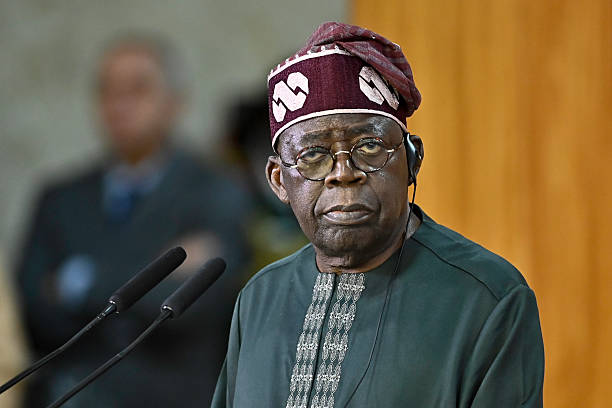
• President Bola Tinubu
A spate of painful reforms is beginning to show results.
When nigeria returned to civilian rule in 1999, Olusegun Obasanjo, the elected president, set out to clean up the economy after years of mismanagement by military governments.
Initially dismissed by critics, by the end of his second term Mr Obasanjo’s liberal policies had tamed inflation, spurred investment and raised annual gdp growth to around 7 percent.
It didn’t last. Over the past decade gdp per person has fallen.
Yet evidence is now mounting that another stretch of “golden years”, as one analyst calls the period following Mr Obasanjo’s liberalisation, may be on the cards.
In the past two and a half years Bola Tinubu, who in Mr Obasanjo’s day was the governor of Lagos and was elected president in 2023, has been enacting his own set of structural reforms.
As he gears up to run for a second term in 2027, they may be starting to pay off.
It is difficult to overstate the mess Mr Tinubu inherited.
When he took office in 2023, the country’s central bank had $7 billion (equivalent to 1.4% of gdp at the time) in obligations it could not meet, prompting international investors to flee en masse.
The bank’s credibility had been dented by a recklessly loose monetary policy, its mismanagement of dwindling foreign-exchange reserves and efforts to maintain an unsustainable tiered exchange-rate system.
Poverty has risen. But it looks as though Mr Tinubu’s bitter medicine is helping.
In 2022 alone the cash-strapped government spent some $10 billion, equivalent to 2.2% of gdp, on a ruinous fuel subsidy.
To fix things, Mr Tinubu’s government got on with a package of drastic structural reforms. It abolished the fuel subsidy and abandoned that multi-tiered system of dollar-pegged exchange rates, largely allowing the naira to float.
The Central Bank aggressively tightened monetary policy to curb the resulting bout of inflation.
The government also moved to improve security in the Niger Delta and offered a range of tax incentives to investors to boost dwindling oil production.
Nearly three years on, Nigeria’s 230 million people, especially the poor and the middle class, are still reeling from increases in fuel and food prices.
Poverty has risen. But it looks as though Mr Tinubu’s bitter medicine is helping.
The annual inflation rate, which hit a nearly 30-year high of 34.8% in December 2024, fell to 15.2% in December 2025.
Growth is returning.
The IMF expects the economy to expand by 4.4% in 2026.
Following two steep devaluations in 2023, the naira has stabilised (see chart).
The Central Bank’s foreign-exchange reserves have risen to $46 billion, their highest level in seven years.
Improvements in macroeconomic stability are restoring investor confidence.
On January 22nd Shell, a British company, said it hopes in 2027 to finalise plans, with partners, to develop a $20 billion offshore oilfield that has been sitting untapped for over 20 years.
Exxon Mobil, an American firm, has committed $1.5 billion to deep water development until 2027.
Local business leaders are more upbeat, too.
Oil-and-gas production is rising, much of it driven by local firms plugging leaks and improving output in onshore projects in the Niger Delta, which has become safer thanks to Mr Tinubu’s focus on security there.
All this should give the government some fiscal breathing room, particularly as the cheaper naira begins to raise the competitiveness of Nigeria’s non-oil exports such as cocoa and cashew nuts.
Recent reforms to taxation and tax collection, Mr Tinubu’s latest project, should help improve revenues further in the coming years.
Falling inflation should eventually begin to ease the cost-of-living pain.
However, even optimists have plenty of reasons to be cautious.
Savings from the fuel subsidy have largely been spent on servicing the public debt, which is still rising as the government continues to borrow against future sales of oil to fund its deficit.
Currently, some 60% of revenues are consumed by debt service.
On January 20th Nigeria’s finance minister said the government hoped to borrow less this year, but current budget projections suggest that is not realistic.
“The government is broke.
There’s nothing to invest in the future, that’s the truth,” says Esili Eigbe of Escap, a Nigerian consultancy.
Unless the government cuts civil-service salaries, another big chunk of spending, or is able to restructure loans to make them cheaper, the extra revenue from recent tax reforms looks unlikely to be available for improving infrastructure or to pay for public health care and education.
“They’ve brought the deficit down, but they don’t seem to show any greater ability to get capital projects out of the door,“ says David Cowan, an economist at Citi, an American bank.
All this means that it will take a long time for ordinary Nigerians, who until now have mostly borne the pain of Mr Tinubu’s reforms, to feel any benefit.
Buying food has been a particular struggle, not just for the 42% of Nigerians who live on less than $3 a day, the World Bank’s definition of extreme poverty, but also for the urban middle class.
The price of a kilo of rice has nearly quadrupled since May 2023, while wages have barely budged.
Even though inflation is now falling, many still struggle to afford enough to eat.
Mr Obasanjo’s reforms in the early 2000s aimed to increase economic dynamism and improve people’s lives by attracting fresh capital investment into newly privatised sectors.
By the end of his second term in 2007, domestic companies were worth $85 billion, up from $3 billion in 1999.
Mr Tinubu, by contrast, has so far focused on restoring stability and reviving the country’s ailing oil-and-gas sector. To bring about more golden years for Nigerians, he needs to go beyond that. ■
Credit: The Economist






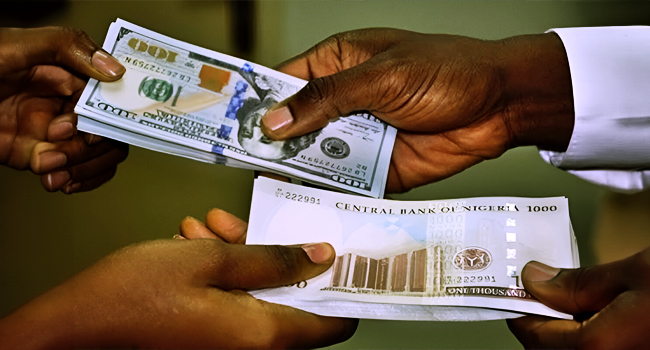
BLACK/ PARALLEL MARKET RATES
₦1370 DOLLAR (USD)
₦1800 POUND (GBP)
₦1510 EURO (EUR)
₦970 CANADIAN DOLLAR (CAD)
₦65 SOUTH AFRICAN RAND (ZAR)
₦350 UAE DIRHAM (AED)
₦190 CHINESE YUAN (CNY)
₦100 GHANAIAN CEDI (GHS)
₦2300 WEST AFRICAN CFA F.(XOF)
₦2200 CENTRAL AFRICAN CFA F.(XAF)
₦850 AUSTRALIAN DOLLAR AUSSIE (AUD)
CBN OFFICIAL RATES
DOLLAR (USD)₦1331.61
POUND (GBP)₦1764.26
EURO (EUR)₦1490.48
SWISS FRANC (CHF)₦1608.23
JAPANESE YEN (JPN)₦8.4
CFA FRANC (XOF)₦2.27
WEST AFRICAN UNIT OF ACCOUNT (WAUA)₦1802.33
CHINESE YUAN (CNY)₦199.01
SAUDI RIYAL (SAR)₦354.83
SOUTH AFRICAN RAND (ZAR)₦80.49
Business
WEF could appoint Lagarde as its next chair, sources say
The WEF’s Board of Trustees, which includes Lagarde herself, was due to meet on November 2 and could elect her as its next chair, said the people close to the organisation, who spoke on condition of anonymity due to the sensitivity of the matter.
•European Central Bank President Christine Lagarde
The World Economic Forum could appoint Christine Lagarde as its next chair as soon as next month, four people close to the organisation told Reuters, meaning she would step down early as European Central Bank chief and trigger a wider reshuffle at the top of the ECB.Lagarde’s ECB term is scheduled to end in October 2027.
Leaving early would give European Union leaders a chance to pick a new ECB President before France’s spring presidential election, which opinion polls suggest the far-right could win, and could pave the way for a deal involving two other senior ECB roles.
The WEF’s Board of Trustees, which includes Lagarde herself, was due to meet on November 2 and could elect her as its next chair, said the people close to the organisation, who spoke on condition of anonymity due to the sensitivity of the matter.
No final decision has been taken yet, they said.
A spokesperson for the WEF said the forum could not confirm when the next full Board of Trustees meeting would take place, but that the aim was to hold one before the end of the year.
Business
Germany plans tax on sugary drinks
The tax is expected to generate additional revenue for the federal government of €690 million in 2027 and €925 million in 2028.
The German cabinet has approved draft legislation to tax sugary drinks in Europe’s biggest economy.
If passed by the German Bundestag, the tax will take effect on 1 July 2027.
The coalition aims to raise revenue for the federal budget while encouraging manufacturers to reduce sugar content and offer healthier products.
The levy is intended to ease pressure on the healthcare system, which faces costs of more than €2 billion every year linked to the high consumption of sugary drinks, which contributes to obesity, diabetes and tooth decay.
According to the federal government, Berlin is using the tax to implement “what associations from the fields of health, science, child protection, and consumer protection have long been demanding.”
The tax is expected to generate additional revenue for the federal government of €690 million in 2027 and €925 million in 2028.


JUST IN: Mob Sets BRT Bus Ablaze After Motorcyclist’s Death in Lagos

BREAKING: DSS Arrests Fugitive Maina Son, Hands Him to EFCC

BREAKING: 5 Arrested Over Imo NYSC Abduction

BREAKING: Lagos Govt Declares Today, Thursday Work-Free to Mark 2026 Ìṣẹ̀ṣe Day

Tech Expert, Zuckerberg trains with UFC champions, Adesanya, Alexander

Organ Trafficking: Ekweremadu bags 10 years in UK prison
-

 Business3 days ago
NAFDAC scolds fake manufacturers: “You are killing Nigerians in order to make money”
-
 Business3 days ago
Oyedele Chairs G-24 Call for Fairer Global Financial System, Affordable Development Financing
-
 Business2 days ago
Naira Exchange Rates For Thursday, October 15
-
 Sports2 days ago
CAF Increases Annual Funding for Member Federations to $700,000
-
 Business1 day ago
Germany plans tax on sugary drinks
-
 Politics2 days ago
Exclusion of candidates from INEC list: CD cautions INEC against manipulation by politicians
-
 News1 day ago
ASCON To Be Rebranded “National School Of Government”
-
 Business1 day ago
WEF could appoint Lagarde as its next chair, sources say