
News
Understanding Mortgage Options in Nigeria’s Real Estate Market by Dennis Isong

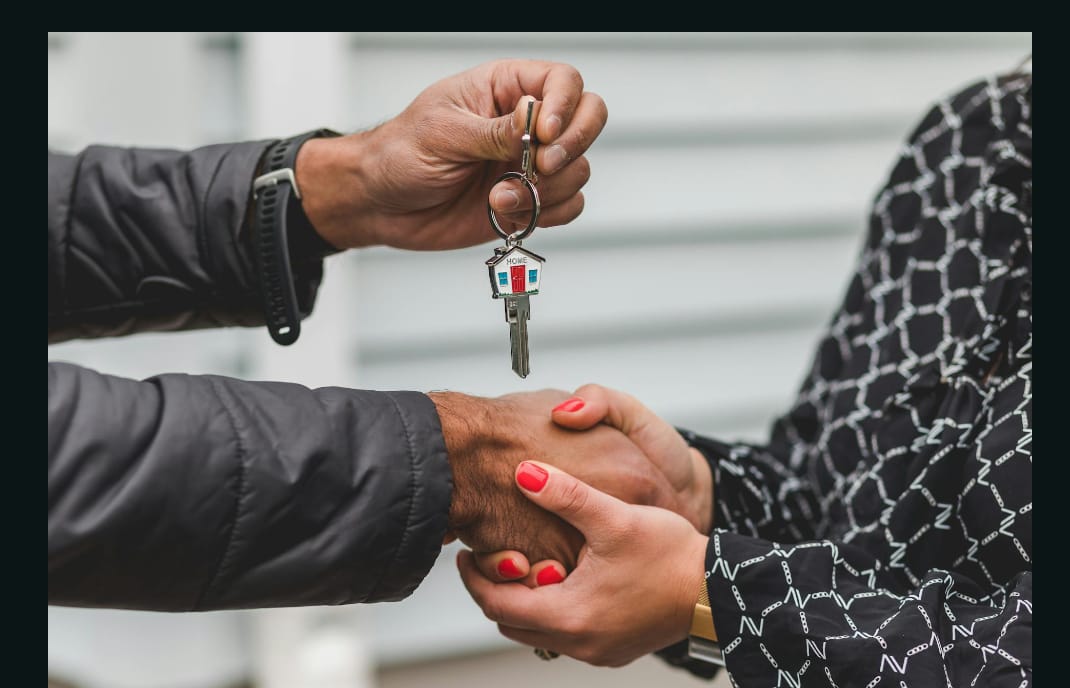
For Nigerians considering a mortgage, thorough research and preparation are essential.
As more Nigerians aspire to become homeowners, understanding the available mortgage options becomes essential.
This article discusses mortgage financing in Nigeria, exploring the various options available to prospective homeowners and investors..
The Nigerian MortgageNigeria’s mortgage industry, while still developing, has made considerable strides in recent years.
The Federal Mortgage Bank of Nigeria (FMBN) and the Nigeria Mortgage Refinance Company (NMRC) play pivotal roles in shaping the mortgage sector.
These institutions work alongside commercial banks and primary mortgage banks to provide various mortgage products to Nigerians.
The mortgage-to-GDP ratio in Nigeria remains relatively low compared to more developed economies, indicating significant room for growth.
However, challenges such as high interest rates, limited long-term funding, and stringent lending criteria have historically hindered widespread mortgage adoption.
Despite these obstacles, recent government initiatives and private sector innovations are gradually making mortgages more accessible to a broader segment of the population.
Types of Mortgage Options
Nigerian homebuyers and investors can choose from several mortgage options, each with its unique features and requirements.
The most common types include:Federal Mortgage Bank of Nigeria (FMBN) Loans:
These are government-backed mortgages designed to provide affordable housing finance to Nigerian workers.
The National Housing Fund (NHF) scheme, administered by the FMBN, allows contributors to access loans at favorable interest rates for home purchase or construction.
Commercial Bank Mortgages: Many commercial banks in Nigeria offer mortgage products to their customers.
These loans typically have higher interest rates compared to government-backed options but may offer more flexibility in terms of loan amounts and repayment periods.
Primary Mortgage Bank Loans: Specialized mortgage institutions provide various home financing options, often with more competitive rates than commercial banks.
These institutions focus exclusively on mortgage lending and may offer more tailored products to meet specific needs.
Rent-to-Own Schemes: Some developers and financial institutions offer rent-to-own arrangements, allowing tenants to gradually build equity in a property while paying rent.
This option can be particularly attractive for those who may not qualify for traditional mortgages.
Cooperative Society Loans: Many Nigerians participate in cooperative societies that pool resources to provide housing loans to members.
These loans often come with lower interest rates and more flexible terms compared to traditional banking options.Eligibility and Requirements
Securing a mortgage in Nigeria typically requires meeting certain eligibility criteria and fulfilling specific requirements. While these may vary depending on the lender and the type of mortgage, common factors include:
Income and Employment:
Lenders generally require proof of stable income and employment. The debt-to-income ratio is a crucial factor in determining loan eligibility and amount.Credit History:
Although Nigeria lacks a comprehensive credit scoring system, lenders may review an applicant’s credit history and repayment record on previous loans.
Down Payment: Most mortgage options in Nigeria require a significant down payment, typically ranging from 20% to 30% of the property’s value.
Some government-backed schemes may offer lower down payment requirements.Property Valuation: The property being purchased or used as collateral must undergo a professional valuation to determine its market value and ensure it meets the lender’s criteria.
Documentation: Applicants must provide various documents, including identification, proof of income, tax clearance certificates, and property-related documents.
Age Limit: Many lenders impose age restrictions, often requiring the mortgage to be fully repaid before the borrower reaches retirement age.
Challenges and Opportunities in Nigerian Mortgage Financing.
While the Nigerian mortgage market continues to evolve, several challenges persist. High interest rates, often in double digits, make mortgages unaffordable for many Nigerians.
The lack of long-term funding sources limits the ability of lenders to offer extended repayment periods, which could make monthly payments more manageable.Land tenure issues and the complexities of property registration in some parts of the country also pose significant hurdles.
The time and cost associated with perfecting property titles can add to the overall expense of obtaining a mortgage.
However, these challenges also present opportunities for innovation in the mortgage sector. Fintech companies are entering the market with digital solutions that streamline the mortgage application and approval process.
Some lenders are exploring alternative credit scoring methods to assess creditworthiness, potentially opening up mortgage access to a broader population.
The government’s ongoing efforts to address housing deficits through initiatives like the Family Homes Fund and the National Housing Programme are creating new opportunities for affordable mortgage financing.
Additionally, the gradual development of the secondary mortgage market through the Nigeria Mortgage Refinance Company (NMRC) is expected to increase liquidity in the sector and potentially lead to more competitive mortgage rates.
Navigating the Mortgage Process.
For Nigerians considering a mortgage, thorough research and preparation are essential.
Prospective borrowers should:
● Compare offerings from multiple lenders to find the best rates and terms.
● Understand all associated costs, including processing fees, insurance, and potential penalties for early repayment.
● Seek professional advice from financial advisors or real estate experts to make informed decisions.
● Consider the long-term implications of the mortgage, including how it aligns with future financial goals and career plans.
● Stay informed about government policies and initiatives that may affect the mortgage market or provide new opportunities for home financing.
As Nigeria’s real estate market continues to grow and evolve, so too will the mortgage options available to its citizens.
By understanding the current landscape and staying informed about new developments, prospective homeowners and investors can make the most of the opportunities presented by mortgage financing in Nigeria’s dynamic real estate sector.
For personalized assistance with your property needs, contact Dennis Isong, a top Lagos realtor specializing in helping Nigerians in the diaspora own property stress-free.Contact: +2348164741041


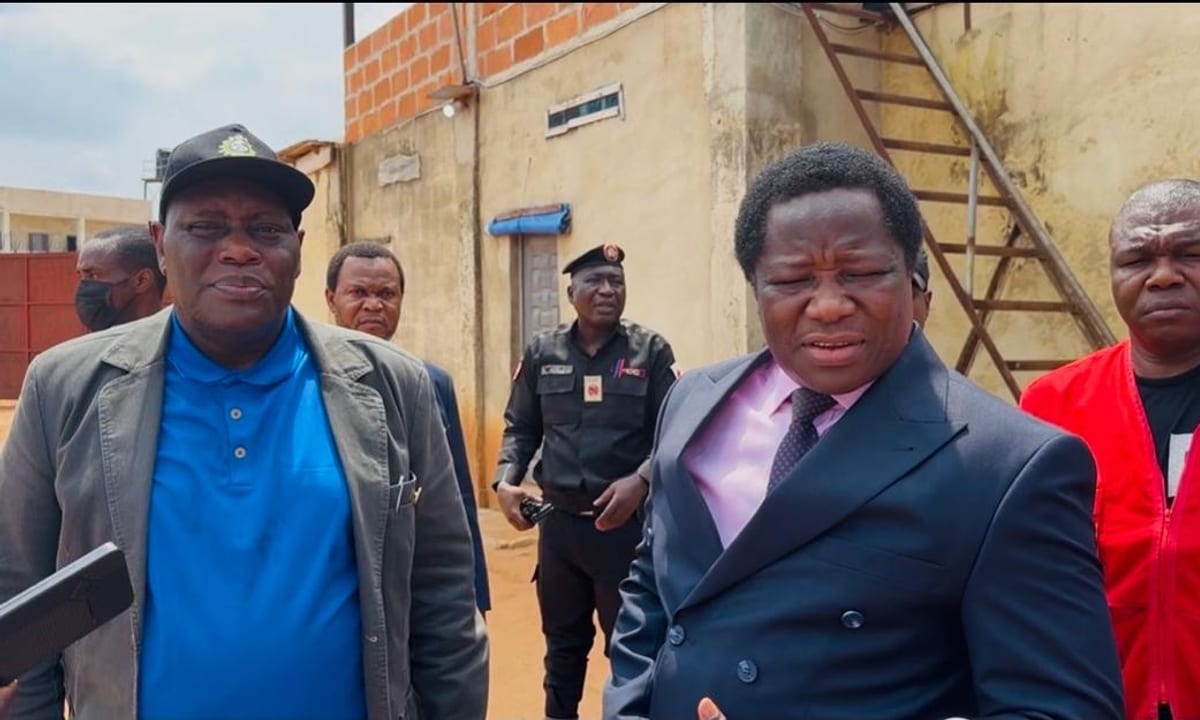
The Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA) and operatives of the Economic and Financial Crimes Commission (EFCC) on Tuesday stormed an illegal Chinese-operated refinery in Ogere-Remo, Ikenne Local Government Area of Ogun State.
The joint operation followed intelligence reports that revealed a well-fenced but crude yet technically sophisticated facility occupying more than three hectares of land.
During the inspection, officials observed underground tanks believed to have been used for heating and processing sludge oil, refining waste products, and substances suspected to be Automotive Gas Oil (AGO), popularly known as diesel. NMDPRA officials immediately sealed the facility.
Ogun State Coordinator of NMDPRA, Dr. Atilola Akinyemi, described the plant as a complete illegality operating without any permit from regulatory authorities.
“The underground storage facility behind the site has an estimated capacity of more than 90,000 litres, complete with underground heating systems, water hydrants for cooling, locally fabricated tanks and silos for separation,” Akinyemi told journalists.
He warned that if such adulterated products entered the market, they would pose serious risks to vehicles and engines. All recovered products have been confiscated by the Federal Government.
Director of the Department of Proceeds of Crime Management at the EFCC, Gbolahan Latona, stressed the need for collective patriotism in tackling economic crimes.
“Upon conclusion of investigation, the suspects will have their day in court and the proceeds of crime will be put to meaningful use,” Latona said.
Watch video below:
News
Sanusi: Critics Are Not Enemies Of The Govt
” It’s not every time people talk about poverty or talk about difficulty that they’re just enemies of the government or making an attack on the president. That is not how to respond to economic distress,” he said.
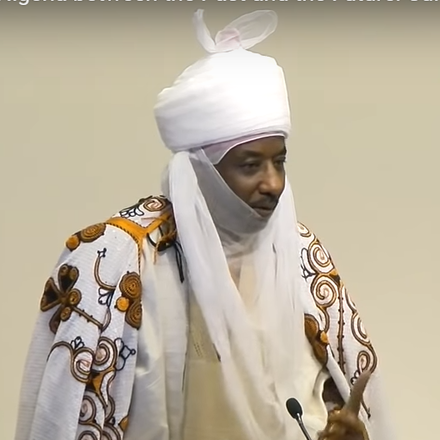
The Emir of Kano, Alhaji Muhammadu Sanusi II, has advised the Federal Government against treating every comment about the administration as an attack on President Bola Tinubu.
The royal father gave the advise on the occasion of the Oxford Global Think Tank Leadership Conference, organised by the Oxford Global Think Tan.
Speaking virtually to the audience at the event, on Tuesday, Sanusi advised the government to tolerate constructive criticism.
“It’s not every time people talk about poverty or talk about difficulty that they’re just enemies of the government or making an attack on the president. That is not how to respond to economic distress,” he said.
News
Urbanisation: Lagos To Fall Behind Luanda as sub-Saharan Africa’s biggest city by 2050
The report titled ‘Sub-Saharan Africa’s Urban Awakening: Catalyzing Economic Growth and Job Creation’, also calculated that sub-Saharan Africa’s urban population will increase by 748 million between 2025 and 2050, reaching about 1.7 billion.

A report conducted by the World Bank and the European Commission’s Joint Research Centre, has projected that Angola’s capital, Luanda,will overtake Lagos as sub-Saharan Africa’s most populous city by 2050, rising by 78 percent from 11.4 million to 20.3 million.
The report titled ‘Sub-Saharan Africa’s Urban Awakening: Catalyzing Economic Growth and Job Creation’, also calculated that sub-Saharan Africa’s urban population will increase by 748 million between 2025 and 2050, reaching about 1.7 billion.
The report estimated that Luanda’s population would increase from 11.4 million in 2025 to 20.3 million in 2050, adding 8.9 million residents over the period.
Lagos, the region’s most populous city in 2025 with an estimated 12.8 million residents, is projected to grow to 16.2 million by 2050, an increase of more than 25 percent.
Despite the growth, Lagos is expected to fall behind Luanda, whose population is projected to exceed that of Nigeria’s commercial hub by 4.1 million.
“Over this period, the population of Angola’s capital city, Luanda, is projected to increase by 78 percent from 11.4 million to 20.3 million.
In doing so, Luanda will overtake Lagos as SSA’s most populous city,” the report said.


Army Deals Major Blow to Terrorists in Niger, Frees 16 Abductees

JUST IN: Ronaldo Ends 23-year Portugal Career, Hangs National Team Boots

JUST IN: Court sacks Mark-led ADC, invalidates Atiku Abubakar’s nomination

BREAKING: Lagos Govt Declares Today, Thursday Work-Free to Mark 2026 Ìṣẹ̀ṣe Day

Tech Expert, Zuckerberg trains with UFC champions, Adesanya, Alexander

Organ Trafficking: Ekweremadu bags 10 years in UK prison
-
 Business2 days ago
Naira Exchange Rates Thursday, 5 Nov 2026
-
 News3 days ago
NMDPRA, EFCC Storm Illegal Chinese Refinery in Ogun (Video)
-
 Politics3 days ago
2027 Elections Campaign: NDC Reacts To Today’s Attack On Peter Obi in Cross River
-
 International3 days ago
Democrats Win US midterm elections
-
 Sports2 days ago
JUST IN: Ronaldo Ends 23-year Portugal Career, Hangs National Team Boots
-
 Politics2 days ago
JUST IN: Court sacks Mark-led ADC, invalidates Atiku Abubakar’s nomination
-
 Crime23 hours ago
Army Deals Major Blow to Terrorists in Niger, Frees 16 Abductees