
Business
6 quick tips to master personal finance in the face of dwindling Nigerian economy
The naira has been on a downward spiral, with the exchange rate for one US dollar reaching an all-time high of 733 naira at the black market and 461 naira officially as of May 2023.


The Nigerian economy has been experiencing a steady decline in recent years, leaving many citizens struggling to navigate the turbulent financial waters. With the naira facing continuous devaluation and a soaring inflation rate, personal finance management has become a crucial survival skill for Nigerians. This article aims to inspire and empower individuals to take charge of their finances, offering practical advice and expert insights to not only survive but thrive in the face of economic challenges.
As of today, the consumer price index (CPI), which measures the rate of change in prices of goods and services, rose to 22.04 percent in March 2023, up from 21.91 percent in the previous month. However, this figure is still alarmingly high, considering the single-digit inflation target set by the Central Bank of Nigeria (CBN). The naira has also been on a downward spiral, with the exchange rate for one US dollar reaching an all-time high of 733 naira at the black market and 461 naira officially as of May 2023. This economic uncertainty has led to job losses, pay cuts, and reduced purchasing power for the average Nigerian.
Despite the bleak outlook, financial experts believe there is hope for Nigerians who are willing to adopt sound personal finance practices. “The key to financial success in a dwindling economy lies in discipline, planning, and investing,” says Amina Mohammed, a renowned financial consultant based in Lagos. “By taking control of your finances and making informed decisions, you can achieve financial freedom and protect yourself from the effects of the unstable naira.”
Here are some practical steps to help you master personal finance in the face of Nigeria’s economic challenges:

1. Create a budget and stick to it
Developing a budget is the foundation of good financial management. List your income and expenses to track your cash flow and identify areas where you can cut back. Prioritize your spending on necessities and avoid impulsive purchases. Sticking to your budget will help you live within your means and prevent unnecessary debt.
2. Build an emergency fund
Having an emergency fund is crucial, especially during times of economic uncertainty. Aim to save at least three to six months’ worth of living expenses in a separate account to cushion yourself against unforeseen crises such as job loss, medical emergencies, or other unexpected expenses.
3. Pay off high-interest debts
High-interest debts can cripple your finances and hinder your ability to save or invest. Make a plan to pay off these debts as quickly as possible, starting with the highest interest rate first. As you pay off each debt, redirect the funds to the next debt on your list, creating a “debt snowball” effect that accelerates your debt repayment process.
4. Diversify your income sources
Depending on a single income stream can be risky, particularly in an unstable economy. Look for ways to generate additional income through side hustles, freelancing, or investments. Diversifying your income sources can provide a financial safety net and increase your overall earning potential.
5. Invest wisely
Investing is a powerful tool to grow your wealth and protect yourself from inflation. However, it’s essential to make informed investment decisions and avoid get-rich-quick schemes. Consult with a financial advisor to determine the best investment options for your risk tolerance and financial goals.

6. Educate yourself on personal finance
Stay informed about financial trends, concepts, and strategies by reading books, attending seminars, or enrolling in online courses. Continuous learning will empower you to make smarter financial decisions and stay ahead of the economic curve.
In conclusion, mastering personal finance in Nigeria’s dwindling economy may seem like an uphill battle, but with determination, discipline, and the right strategies, it is possible to achieve financial stability and success. By taking charge of your financial future, you can create a brighter outlook for yourself and your family, safeguarding your wealth against the fluctuations of the naira and the challenges of the Nigerian economy.




Africa’s richest man, Aliko Dangote, and Kenyan President William Ruto are currently breaking ground on a landmark $16 billion oil refinery in Lamu, on Kenya’s northern coast.
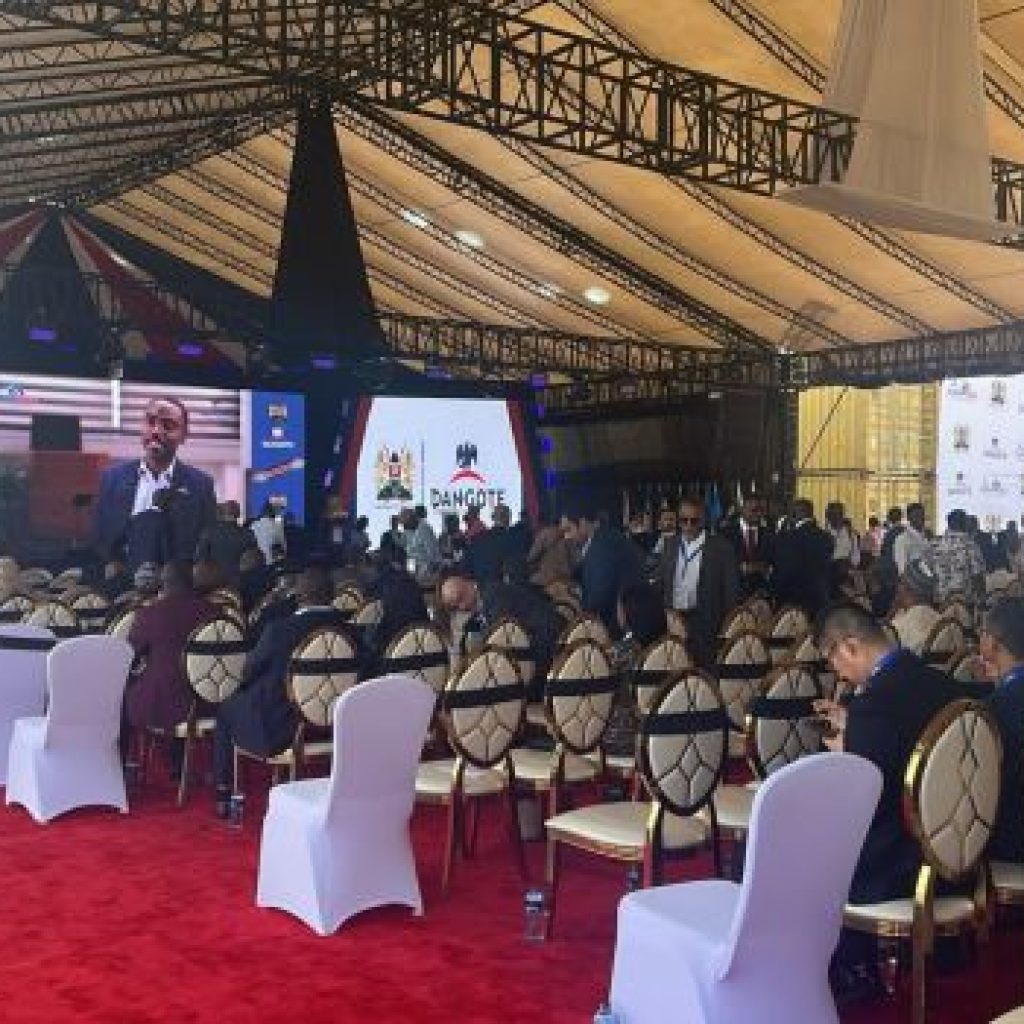
The ceremony, held on Wednesday, September 30, 2026, formally launches construction of the 700,000-barrel-per-day facility, which is set to become the largest refinery in East Africa and the second-largest on the continent after Dangote’s plant in Lekki, Nigeria. The project aims to replicate the success of the Nigerian refinery by processing crude for regional markets, reducing East Africa’s long-standing dependence on imported refined petroleum products, lowering fuel costs, and conserving scarce foreign exchange.
Several African leaders are attending the groundbreaking, including the presidents of Uganda and Ethiopia, along with other regional heads of state and former Nigerian President Olusegun Obasanjo. The event underscores growing continental efforts to process raw materials locally rather than exporting crude and importing finished fuels.
Once completed around 2030, the Lamu refinery is expected to supply Kenya and neighbouring countries such as Uganda, South Sudan, Rwanda, and others. Officials project it will create between 50,000 and 60,000 jobs and stimulate related industries, including petrochemicals and bitumen production. The complex will also feature a 1,000-megawatt power plant, with plans to sell a portion of the electricity to the Kenyan government.
Dangote has offered East African governments a combined 30% equity stake in the project. Financing is structured with roughly 70% debt and 30% equity. The facility is located near Lamu’s deep-water port, chosen for its strategic advantages in handling large-scale industrial operations.

While the project has faced some local land-related protests and a court order maintaining the status quo pending a hearing, the groundbreaking is proceeding as planned. Dangote has dismissed the challenges and reaffirmed that construction will move forward, with the plant targeted for completion in under four years.
The development is being hailed as one of Kenya’s biggest infrastructure investments since independence and a major step toward regional energy security and industrialisation.

The Malindi Environment and Land Court has declined to issue orders stopping the launch and construction of the planned KSh 2 trillion Dangote Oil Refinery in Lamu County.
In a ruling made public on Monday, 28 September 2026, the court instead directed both parties to maintain the status quo on the disputed land in the Hindi/Manda Magogoni area until the matter is heard on 14 October 2026.
The case was brought by 133 residents of Chandavai. They claim the land is their ancestral heritage, where their families have lived and farmed for generations. The residents say they do not oppose development but want their land rights recognised before the project proceeds.
The court ordered the government and other respondents to file their responses within 14 days. The application is scheduled for hearing on 14 October 2026.
The groundbreaking ceremony for the refinery is expected to go ahead as planned on Wednesday, 30 September 2026. While the court has not halted the ceremony at this stage, the status quo order means activities on the disputed site may be restricted pending the October hearing.
Business
Oil Rises As US Rejects Iran Proposal
Iran said it is waiting for a definitive US response to its seven-day proposal to reopen the strait and other demands, adding that it will not ease its conditions after Trump rejected Tehran’s latest plan.

Brent crude climbed above $106 per barrel on Monday, recovering losses from the previous session after President Donald Trump rejected Iran’s latest proposal to reopen the Strait of Hormuz, raising concerns that the restoration of oil flows through the critical waterway could face further delays.
Trump also said Tehran had overplayed its hand and expects negotiations to resume this week.
Meanwhile, Iran said it is waiting for a definitive US response to its seven-day proposal to reopen the strait and other demands, adding that it will not ease its conditions after Trump rejected Tehran’s latest plan.
Elsewhere in the Middle East, tensions remain high as Saudi Arabia intercepted Houthi drones heading toward Riyadh, along with a missile targeting Khamis Mushait in the south.
Alerts were also issued in Abha and Jazan, where Aramco operates energy facilities.
In the US, Trump is considering a ban on diesel exports as part of efforts to address elevated fuel prices.


Plane Makes Emergency Landing After Pilots Fight in Cockpit

Atiku Demands Release of 5 Arrested Over ‘Tinubu Must Go’ T-Shirts

ON-GOING: Dangote $16 billion refinery groundbreaking holds in Kenya (Images)

Tech Expert, Zuckerberg trains with UFC champions, Adesanya, Alexander

Organ Trafficking: Ekweremadu bags 10 years in UK prison

SAINT OBI: Between his marriage and his death
-
 Business3 days ago
NGX Debuts Invest WhatsApp Channel
-
 Business3 days ago
SEC Highlights Focus of National Capital Market Conference 2026
-
 Sports3 days ago
Flamingos win WAFU B U-17 women’s tournament
-
 Business3 days ago
Naira To Dollar, Pound, Euro …Today, September 28
-
 Entertainment2 days ago
Madonna and Taylor Swift win big at the MTV VMAs
-
 Business3 days ago
Ghana Moves to Cut Domestic Airfares as Ticket Prices Stay High
-
 News2 days ago
JUST IN: Fire Engulfs Lagos Customs Command Office
-
 News2 days ago
Nigeria is 66, Thursday October 1