
Business
MAN Urges CBN To Consider CRR Cut Next Phase of Monetary Easing
MAN’s call came against the backdrop of the CBN’s latest monetary policy decision, in which the apex bank cut the Monetary Policy Rate (MPR) by 350 basis points to 23 per cent from 26.5 per cent, while retaining the CRR at 45 per cent for Deposit Money Banks and 16 per cent for Merchant Banks.

The Manufacturers Association of Nigeria (MAN) has placed access to credit at the centre of the next phase of monetary easing by the Central Bank of Nigeria.
The association argues that lower headline borrowing costs alone may not translate into stronger industrial activity unless banks have sufficient liquidity to extend credit to productive businesses.
MAN, therefore, urges CBN to reduce the Cash Reserve Ratio (CRR), currently at 45 per cent for Deposit Money Banks, arguing that the high reserve requirement is limiting the funds available for lending to manufacturers and other productive sectors of the economy.
MAN’s call came against the backdrop of the CBN’s latest monetary policy decision, in which the apex bank cut the Monetary Policy Rate (MPR) by 350 basis points to 23 per cent from 26.5 per cent, while retaining the CRR at 45 per cent for Deposit Money Banks and 16 per cent for Merchant Banks.
The CBN also retained the Liquidity Ratio at 30 per cent.
Director-General of MAN, Segun Ajayi-Kadir, welcomed the reduction in the MPR, describing it as a positive development that aligns with manufacturers’ expectation that monetary easing should follow a period of economic stabilisation.
According to him, the reduction signals a gradual departure from the exceptionally tight monetary conditions that have prevailed in recent periods and contributed to the weak performance of the manufacturing sector.
He said the lower MPR should help reduce borrowing costs and improve the operating environment for businesses, particularly manufacturers that depend heavily on working capital and investment financing.
“The adjustment is expected to lower the borrowing cost and improve the operating environment for businesses, particularly manufacturers whose activities depend heavily on working capital and investment financing,” Ajayi-Kadir said.
He added that the reduction in the policy rate would support manufacturers’ ability to finance inventory, raw materials, production cycles, equipment acquisition and business expansion.
However, MAN argued that the impact of the MPR cut could be weakened by the continued high CRR.
Ajayi-Kadir said retaining the CRR at 45 per cent for Deposit Money Banks and 16 per cent for Merchant Banks means that a substantial proportion of banks’ deposits would remain sterilised as reserves rather than being deployed as credit to businesses.
“While reserve requirements remain important for financial and monetary stability, the relatively high CRR may continue to constrain the proportion of deposits available for lending to productive sectors,” he said.
According to MAN, reducing the CRR would complement the MPR cut by improving banking-system liquidity and increasing the pool of funds available for credit to manufacturers.
“It is obvious that improved liquidity conditions could increase credit availability and strengthen businesses’ ability to meet short-term financing needs, but the benefits of the MPR reduction may not be fully realised if credit expansion to the real sector remains constrained because of the high CRR rate that reduces the available funds for lending or investment,” Ajayi-Kadir said.
.
Business
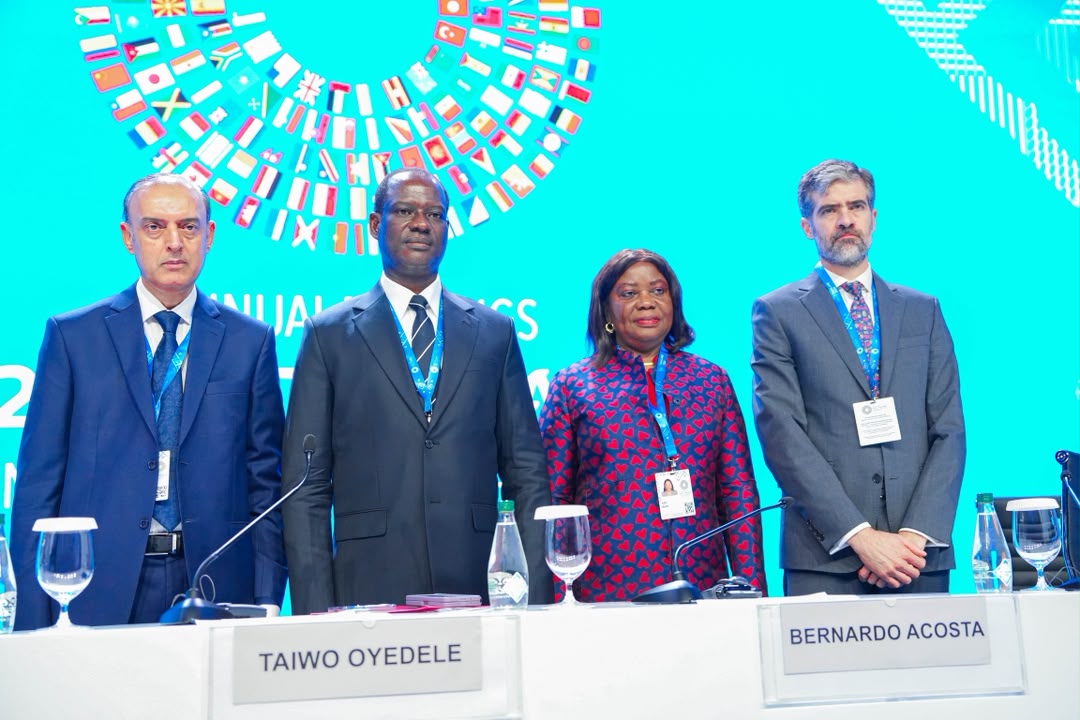
Oyedele Chairs G-24 Call for Fairer Global Financial System, Affordable Development Financing
The meeting concluded that domestic reform alone will not shield developing economies from external shocks — affordable finance, effective debt resolution, fairer representation in international institutions, and sustained cooperation are equally necessary.
Business
NAFDAC scolds fake manufacturers: “You are killing Nigerians in order to make money”
He warned that the circulation of counterfeit drinks posed a serious public health concern, urging suspected manufacturers to abandon the illegal trade.

“You are killing Nigerians in order to make money,which is not good.”
That’s the National Agency for Food and Drug Administration and Control (NAFDAC) scolding Nigerians caught in the act of counterfeiting drinks.
The occasion was at Zamfara Plaza, BBA Trade Fair Complex, along the Badagry Expressway, Ojo, Lagos State.
The Assistant Director of the Investigation and Enforcement Directorate of NAFDAC, Mr Kunle Ojo, who led the enforcement said the agency caught some of the suspects in the act and recovered drums, filters, packaging materials, a heating device and other equipment allegedly used in the illicit production process.
The suspects, identified as Okafor and John, were arrested during an enforcement operation in a two-storey building where equipment and materials allegedly used to repackage and produce counterfeit alcoholic and energy drinks where discovered.
The raid, according to NAFDAC, followed credible intelligence and surveillance on suspected counterfeiters operating within the Trade Fair International Market.
He warned that the circulation of counterfeit drinks posed a serious public health concern, urging suspected manufacturers to abandon the illegal trade.


Shell has agreed to sell its entire interest in the Shell Nigeria Gas Group, which runs a domestic natural gas distribution network, to Nigerian energy firm Vaaris Energy Limited.
The deal, announced on Tuesday, October 13, 2026, covers Shell Petroleum B.V.’s full stake in the business. Shell Nigeria Gas, established in 1998, operates about 170 kilometres of pipelines across Ogun, Abia and Rivers states and supplies more than 130 industrial and commercial customers. Financial terms were not disclosed. Completion remains subject to regulatory approvals and other conditions.
Shell said the business will continue operating as normal and serving customers until the transaction closes. The company does not participate in upstream production, LNG or international gas trading through this unit.
Elohor Aiboni, Shell’s Country Chair in Nigeria, said: “Shell Nigeria Gas has served industrial and commercial customers in Nigeria for more than 25 years, supported by the commitment and expertise of its people. We believe this agreement provides a much stronger platform for the business’ next chapter under new ownership. Shell continues to focus on strategic Deepwater and Integrated Gas positions in Nigeria.”
The sale forms part of Shell’s broader strategy under CEO Wael Sawan to simplify its portfolio and concentrate on higher-return assets. It follows the company’s completed exit from onshore oil production in Nigeria, when it sold the Shell Petroleum Development Company to the Renaissance consortium in 2025.
Vaaris Energy is a privately held Nigerian company with interests across the oil and gas value chain and an existing operational presence in the country.


Sanwo-Olu Appoints Olatunbosun Ogunbanwo, 5 Others as Perm Secs

Exclusion of candidates from INEC list: CD cautions INEC against manipulation by politicians

Oyedele Chairs G-24 Call for Fairer Global Financial System, Affordable Development Financing

Tech Expert, Zuckerberg trains with UFC champions, Adesanya, Alexander

BREAKING: Lagos Govt Declares Today, Thursday Work-Free to Mark 2026 Ìṣẹ̀ṣe Day

Organ Trafficking: Ekweremadu bags 10 years in UK prison
-
 Business3 days ago
Nigeria’s ₦33bn Fruit Import Bill Exposes Missed Opportunities in Jos
-
 Business3 days ago
Naira To Dollar, Pound ,Euro …Rates For Monday, October 12
-
 Politics3 days ago
BEWARE: Fake 2027 Gov’ Candidates List Circulating Online — INEC Raises Alarm
-
 News3 days ago
Forbes Scores GTBank Best Employers 2026
-
 Politics3 days ago
2027: 119 Women Jostle For State’s Governors
-
 Business2 days ago
Dangote Refinery IPO Attracts N8.61trn in Subscriptions, Four Times Offer
-
 News2 days ago
BREAKING: Fire Engulfs First Bank Branch Along Abuja-Keffi Road
-

 Business3 days ago
Afreximbank Hails Africa Credit Rating Agency