
Business
Germany plans tax on sugary drinks
The tax is expected to generate additional revenue for the federal government of €690 million in 2027 and €925 million in 2028.

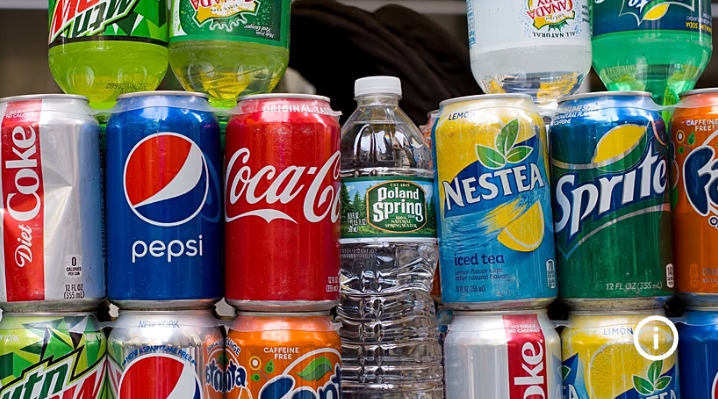
The German cabinet has approved draft legislation to tax sugary drinks in Europe’s biggest economy.
If passed by the German Bundestag, the tax will take effect on 1 July 2027.
The coalition aims to raise revenue for the federal budget while encouraging manufacturers to reduce sugar content and offer healthier products.
The levy is intended to ease pressure on the healthcare system, which faces costs of more than €2 billion every year linked to the high consumption of sugary drinks, which contributes to obesity, diabetes and tooth decay.
According to the federal government, Berlin is using the tax to implement “what associations from the fields of health, science, child protection, and consumer protection have long been demanding.”
The tax is expected to generate additional revenue for the federal government of €690 million in 2027 and €925 million in 2028.
Business
WEF could appoint Lagarde as its next chair, sources say
The WEF’s Board of Trustees, which includes Lagarde herself, was due to meet on November 2 and could elect her as its next chair, said the people close to the organisation, who spoke on condition of anonymity due to the sensitivity of the matter.
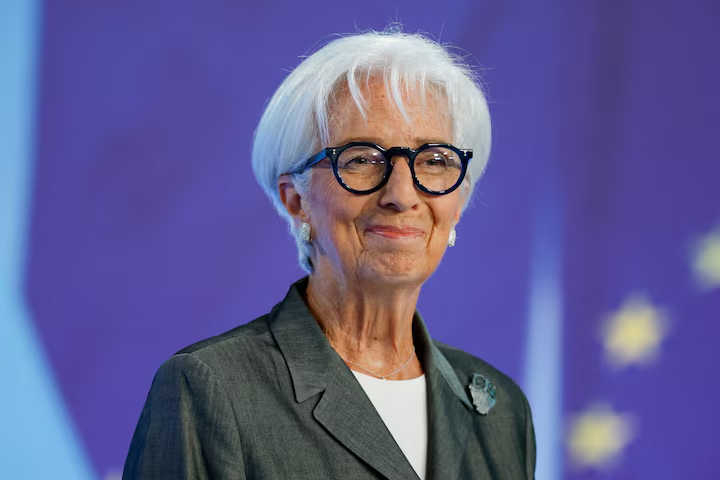
•European Central Bank President Christine Lagarde
The World Economic Forum could appoint Christine Lagarde as its next chair as soon as next month, four people close to the organisation told Reuters, meaning she would step down early as European Central Bank chief and trigger a wider reshuffle at the top of the ECB.Lagarde’s ECB term is scheduled to end in October 2027.
Leaving early would give European Union leaders a chance to pick a new ECB President before France’s spring presidential election, which opinion polls suggest the far-right could win, and could pave the way for a deal involving two other senior ECB roles.
The WEF’s Board of Trustees, which includes Lagarde herself, was due to meet on November 2 and could elect her as its next chair, said the people close to the organisation, who spoke on condition of anonymity due to the sensitivity of the matter.
No final decision has been taken yet, they said.
A spokesperson for the WEF said the forum could not confirm when the next full Board of Trustees meeting would take place, but that the aim was to hold one before the end of the year.
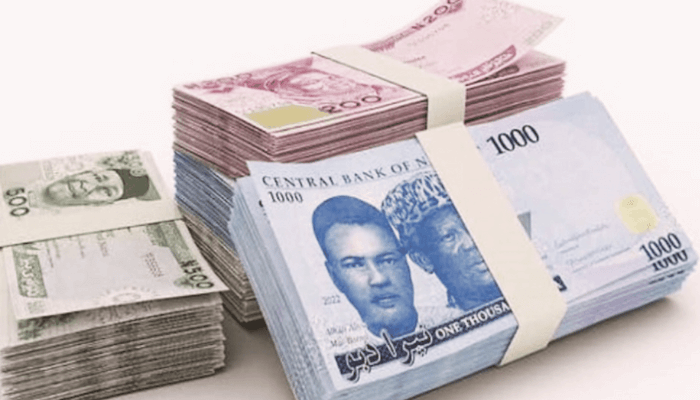
BLACK (PARALLEL) MARKET RATES
₦1370 DOLLAR (USD
₦1800 POUND (GBP)
₦1500 EURO (EUR)
₦970 CANADIAN DOLLAR (CAD)
₦65 SOUTH AFRICAN RAND (ZAR)
₦350 UAE DIRHAM (AED)
₦190YUAN (CNY)
₦2300CFA F.(XOF)
₦2200CFA F.(XAF)
₦850AUSSIE (AUD)SELL₦1000
Official CBN Exchange Rates
DOLLAR (USD)₦1332.59
POUND (GBP)₦1765.55
EURO (EUR)₦1491.57
SWISS FRANC (CHF)₦1590.77
JAPANESE YEN (JPN)₦8.39
CFA FRANC (XOF)₦2.27
WEST AFRICAN UNIT OF ACCOUNT (WAUA)₦1802.33
CHINESE YUAN (CNY)₦199.10
SAUDI RIYAL (SAR)₦354.92
SOUTH AFRICAN RAND (ZAR)₦80.37
Business
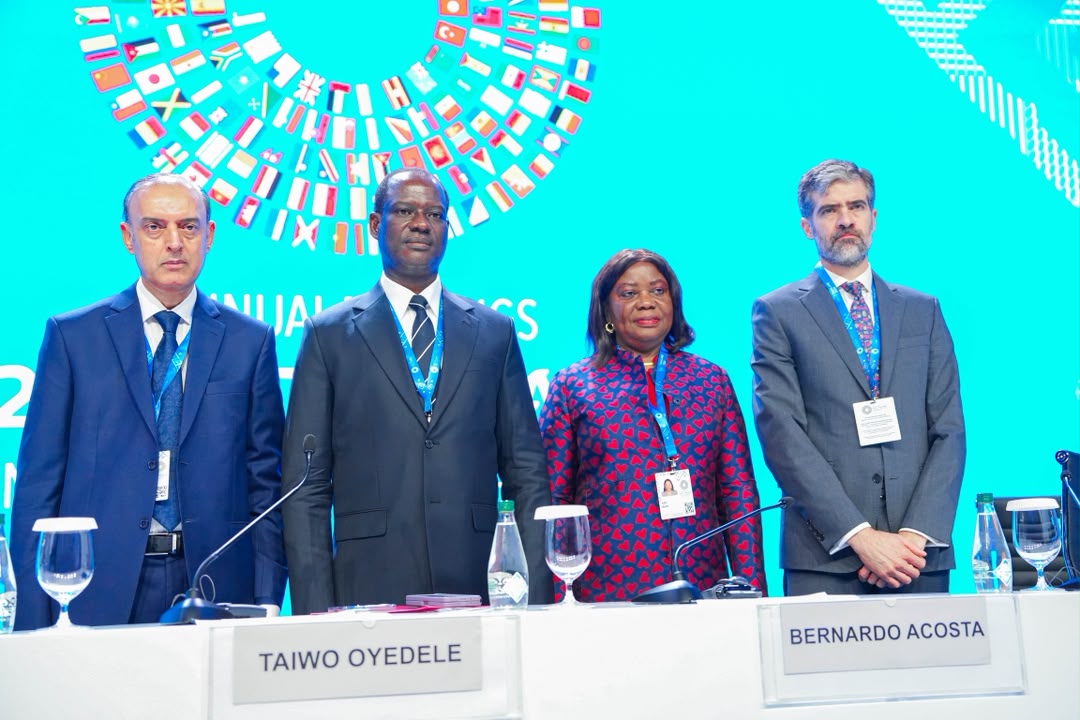
Oyedele Chairs G-24 Call for Fairer Global Financial System, Affordable Development Financing
The meeting concluded that domestic reform alone will not shield developing economies from external shocks — affordable finance, effective debt resolution, fairer representation in international institutions, and sustained cooperation are equally necessary.


WEF could appoint Lagarde as its next chair, sources say

Germany plans tax on sugary drinks

ASCON To Be Rebranded “National School Of Government”

Tech Expert, Zuckerberg trains with UFC champions, Adesanya, Alexander

BREAKING: Lagos Govt Declares Today, Thursday Work-Free to Mark 2026 Ìṣẹ̀ṣe Day

Organ Trafficking: Ekweremadu bags 10 years in UK prison
-
 Business2 days ago
Dangote Refinery IPO Attracts N8.61trn in Subscriptions, Four Times Offer
-
Business2 days ago
Top 10 Highest-Paid CEOs in Nigeria
-

 Business3 days ago
AI to eliminate 40% of global jobs – IMF boss
-
 Business2 days ago
Naira Exchange Rates To Dollar , Pound ,Euro, … Tuesday, October 13
-
 Business2 days ago
Global smartphone shipments fall 20% in Q3 2026, lowest in 14 years
-

 International3 days ago
JUST IN: Pope Leo XIV to Undergo Surgery for Early-Stage Lung Nodule
-
 International2 days ago
Child marriage in southern Germany: Over 350 cases recorded, some brides as young as 11
-
Sports2 days ago
Rwanda to host F1’s first race in Africa since 1993